Mental accounting bias is the reason a $1,000 bonus gets spent differently than $1,000 sitting in savings. Same amount. Same buying power. Your brain treats them like they came from different planets.
This bias shows up everywhere in investing. It is why "house money" gets thrown at bets you would never make with your own paycheck. Economist Richard Thaler named the pattern decades ago, and it still wrecks portfolios today.
Understanding mental accounting bias is the first step to spotting it before it costs you money.
What is mental accounting bias?
Mental accounting bias is the tendency to treat money differently depending on where it came from. Economists call this a violation of fungibility, the idea that a dollar is a dollar no matter its source.
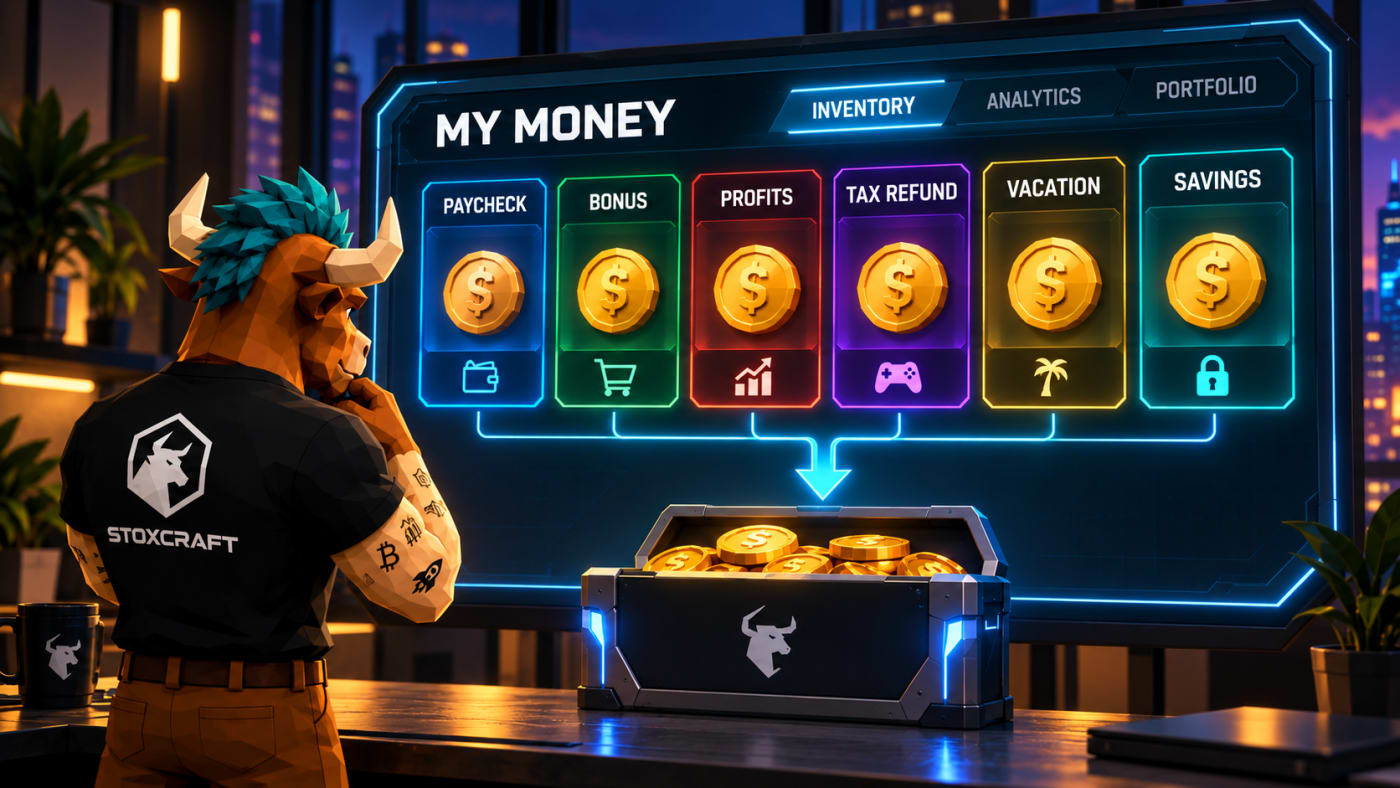
In theory, your paycheck, your bonus, and your portfolio gains should all count the same toward your net worth. In practice, most people build separate mental buckets: rent money, fun money, savings, and "extra" money.
Richard Thaler coined the term after noticing people make inconsistent choices depending on which bucket a dollar sits in. The same $100 feels sacred in one account and disposable in another.
Why house money gets spent more recklessly
The most common version of mental accounting bias in investing is the house money effect. Investors treat profits from a winning trade as free money instead of real capital.
This traces back to a casino experiment. Gamblers who won earlier bets took bigger risks with their winnings than they ever would with cash from their own wallet. The market does not know which pile a dollar came from. Only your brain does.
Try it yourself below. Move both sliders and watch where your instinct lands.
Most people set the risk slider higher on profits than on original capital, even though both piles are worth exactly $2,000. That gap is mental accounting bias, live and measurable.
How mental accounting shows up in your portfolio
This bias does not stay confined to a casino table. It quietly reshapes real investing decisions.
Retail investors who caught the 2021 GameStop (GME) rally are a clean example. GameStop's stock surged 1,600% at one point in January 2021, and plenty of traders who cashed out treated the windfall as house money. They poured it into riskier plays than the one that made them rich in the first place.
This connects directly to risk tolerance. Your risk tolerance should reflect your total financial picture, not shift depending on which account a gain landed in. Mental accounting breaks that logic entirely.
It shows up in smaller ways too. Investors refuse to touch a "vacation fund" while carrying credit card debt. They hold a losing position because selling it would make the loss feel real in that one mental account, even as the same dollars sit untouched elsewhere.
The tax refund is the same story in a different costume. A refund is money you already earned and overpaid to the government. Yet consumer psychologists find people spend refunds more freely than paycheck income precisely because a refund feels like a windfall rather than wages. The label on the money changes the behavior. The math never does.
How to counteract mental accounting bias
Mental accounting bias is a close cousin of the disposition effect, the tendency to sell winners too early and hold losers too long. Both come from treating positions as separate stories instead of parts of one portfolio. A gain in one account gets cashed out fast because it feels like a real win. A loss in another account gets held forever because closing it would make the loss official. Neither decision has anything to do with what the stock is actually worth going forward.
Fixing this bias does not require a finance degree. It requires treating every dollar the same, on purpose, every single time.
- Track your net worth as one number, not a collection of separate pots.
- Size every position against your total portfolio, not which account the cash sits in.
- Before reinvesting a gain, ask if you would make the same trade with paycheck money.
- Set a rule for windfalls in advance, before the windfall actually arrives.
Stoxcraft's Academy has a deeper breakdown of the mental biases that quietly hurt investors, including how this one stacks with anchoring and overconfidence. If a winning streak has ever made your next trade feel bigger and less researched, the Academy's piece on overconfidence and regret goes further into fixing that pattern too.
Every dollar in your account is worth exactly the same
A dollar is a dollar whether it came from your job, a dividend, or a meme stock rally. Mental accounting bias convinces you otherwise, and that conviction gets expensive.
The fix is not complicated. Stop labeling money by its origin story. Judge every position by the same standard, regardless of which bucket it technically sits in.
Once you see this bias, it is hard to unsee it. That alone puts you ahead of most of the market.
Next time a gain lands in your account, run the same one-line test before you touch it. If the trade would not make sense with paycheck money, it does not make sense with profit money either. The dollar cannot tell the difference. You should not either.