Figuring out how to invest an inheritance usually starts at a rough moment. Someone you cared about is gone. Now a pile of money sits in your account, and everyone has an opinion.
You're far from alone. Baby boomers are sitting on about $93 trillion in assets. Visa estimates about $36 trillion from boomers outside the richest 1% will reach heirs within 20 years.
A 2012 Ohio State study tracked young baby boomers who inherited money. Of those heirs, 34.9% ended up with the same or less wealth. Among those who got $100,000 or more, 18.7% spent or lost all of it.
Why you shouldn't rush to invest an inheritance
Grief and big money decisions don't mix. Choices made in the first few weeks are hard to undo.
The simple fix is to park the money first. A high-yield savings account or a money market fund keeps it accessible and earning something. Give yourself a few months before you commit to anything big.
Bank deposits are FDIC-insured up to $250,000 per bank, so split bigger sums. Money market funds carry no FDIC coverage at all.
Parked cash has a real cost. It misses market gains and can trail inflation once interest is taxed. Treat the pause as planning time, not a strategy.
Your brain will also try to file this money as fun money. That habit is called mental accounting, and it's one reason windfalls leak away.
What kind of inheritance you received changes the plan
Not every inheritance shows up as cash. Each type comes with its own rules, and some come with deadlines.
Inherited cash and bank accounts
Cash is the simplest case. You can park it, plan, and invest on your own schedule. In the US, there's no federal inheritance tax, though a handful of states charge one.
Inherited stocks and funds
Inherited shares usually come with a tax break in the US. The cost basis resets to the value on the date of death. That's called a stepped-up basis, and it can wipe out years of taxable gains.
The bigger risk is concentration. If a parent held one company for 30 years, you may now own a single-stock bet. Selling part of it to build real diversification is worth a serious look.
The step-up makes that move cheap. Selling within the first months usually triggers little or no capital gains tax.
The step-up does not apply to IRAs or 401(k)s. Those follow separate rules, covered below.
Inherited IRAs and 401(k) accounts
Inherited retirement accounts follow their own clock. Most non-spouse heirs must empty an inherited IRA or 401(k) within 10 years.
If the owner had already started required withdrawals, you must also take yearly ones. Missing one can trigger a 25% penalty. Withdrawals from traditional accounts also count as taxable income.
Rules differ by country and change often. Talk to a tax pro before you sell or withdraw anything.
Fix your foundation before you invest an inheritance
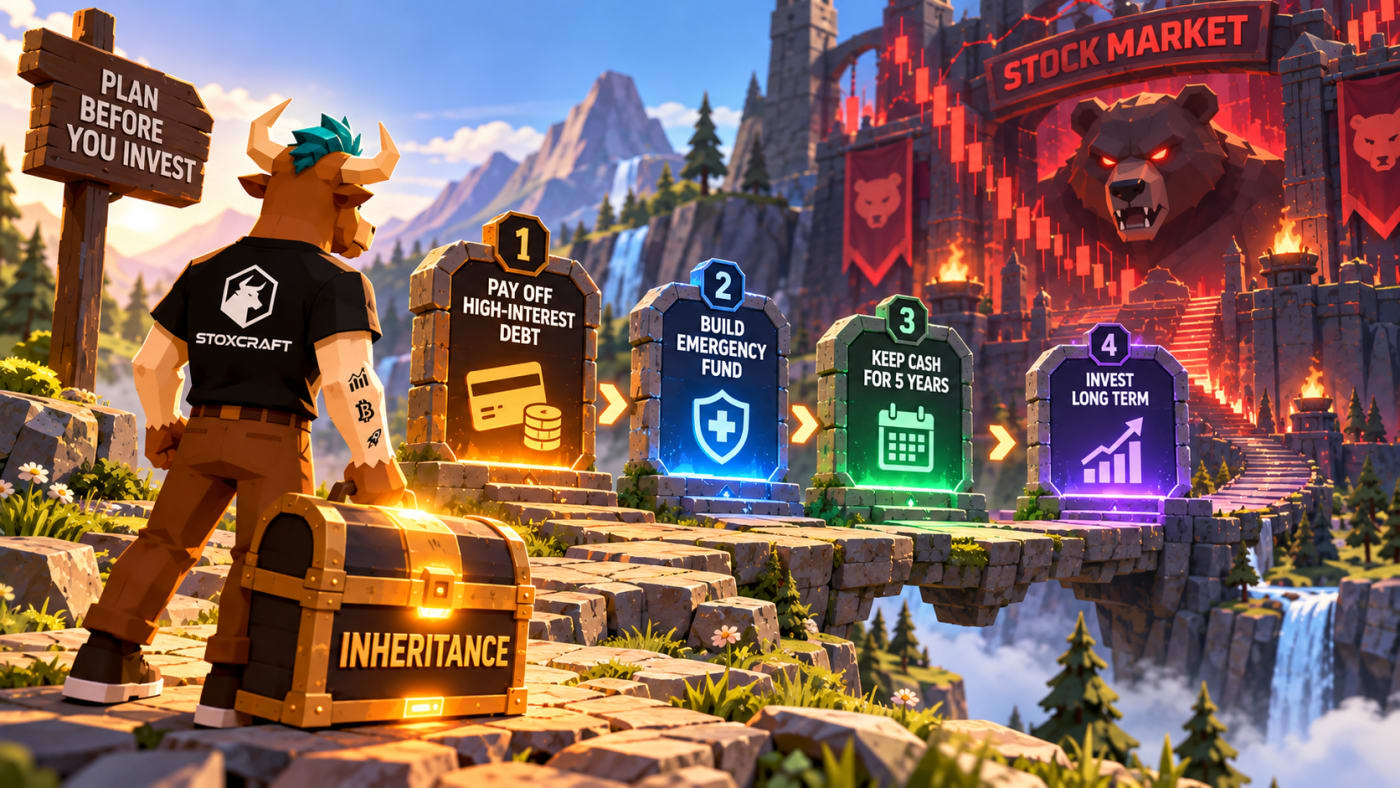
Investing comes after the boring stuff. Skipping it is like walking into a boss fight with half your health bar.
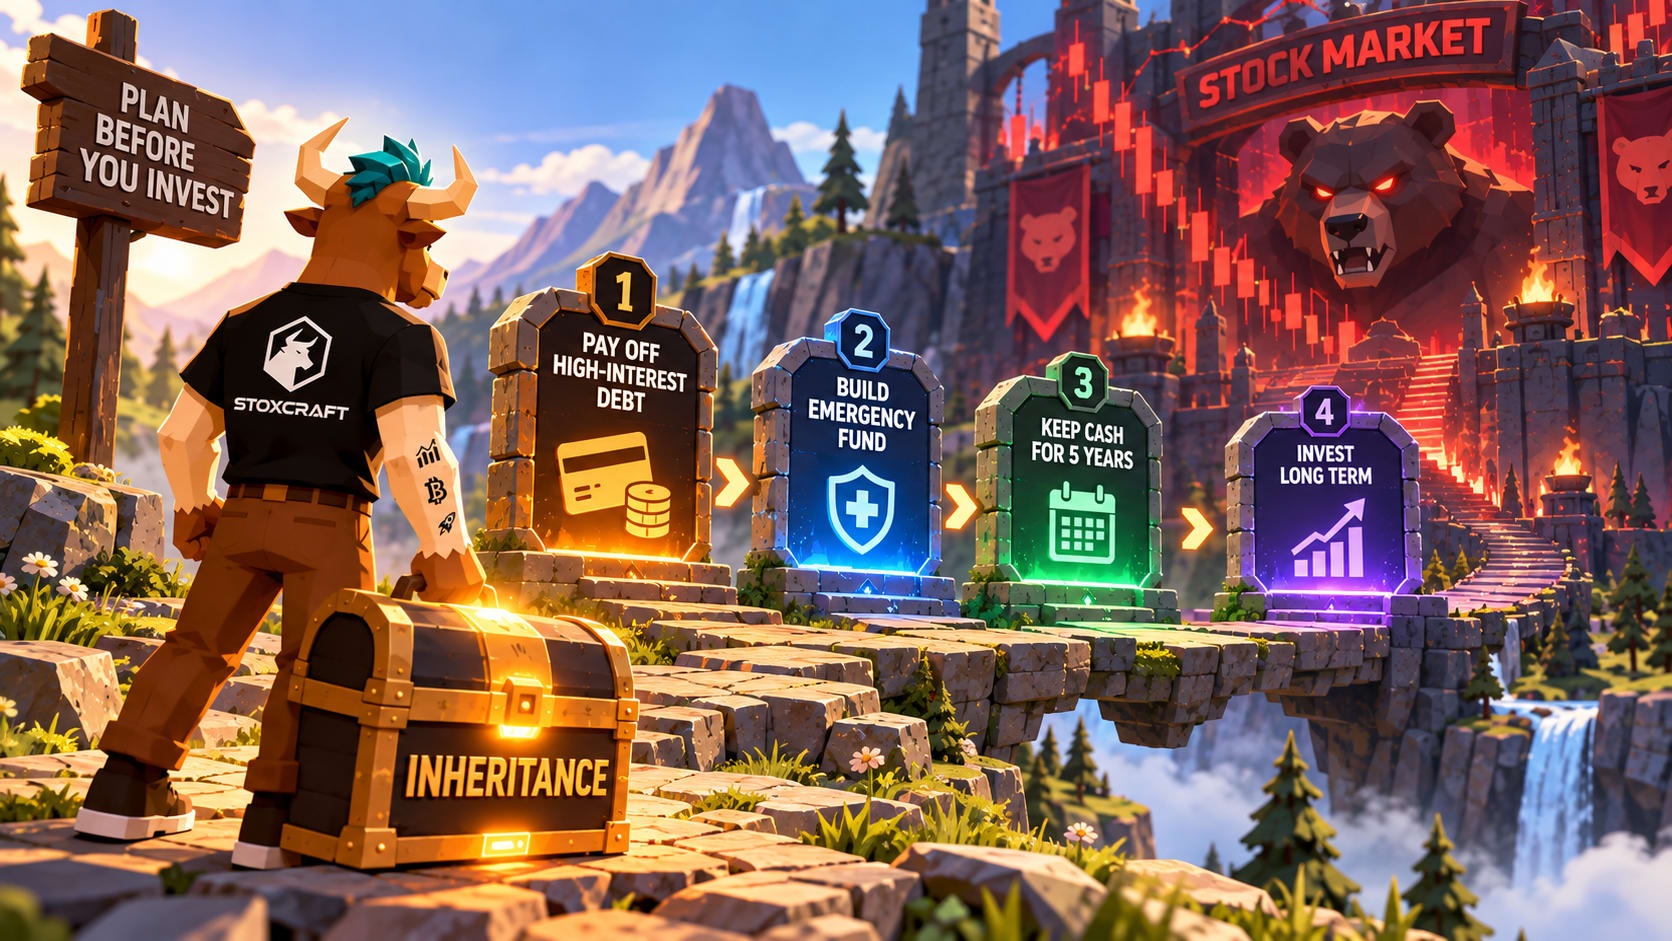
Work through these steps in order before a single dollar goes into the market.
Credit cards often charge over 20% interest. Paying one off is a guaranteed return that no stock can promise. That step doesn't need to wait out the pause.
Money you need within five years doesn't belong in stocks. A bear market can cut prices by 20% or more and take years to recover.
No clear goals yet? Start there. The Stoxcraft Academy lesson on how to set financial goals walks through it step by step.
Lump sum or dollar cost averaging for inherited money
Once the foundation is set, one big question is left. Do you invest everything at once, or spread it out over time?
Dollar cost averaging means investing fixed amounts on a set schedule. Lump sum means putting it all in today. The walkthrough below shows how fixed monthly buys smooth out your average price.
Smoother feels safer. The math still favors the lump sum. Vanguard found lump sum beat dollar cost averaging 68% of the time between 1976 and 2022.
Interest on cash still waiting to be invested narrows that edge a little. Counting interest, lump sum still won 65% of the time.
The reason is simple. Markets rise more often than they fall, so cash on the sidelines usually misses gains. That's the core idea behind why time beats timing in the Stoxcraft Academy.
Gradual buying does win in one situation. It came out ahead in the worst outcomes, like a sharp drop right after investing.
Inheritances add one twist. A loss right after a loved one dies can feel much worse than the math says. If a 20% drop would make you sell, spread your buys over a few months.
Keep the window short. Vanguard found longer phase-ins lose to lump sum more often and suggests about three months. The months you spent parked add to your time out of the market.
A split works too. Invest half now and phase in the rest. For the full data on both sides, read dollar cost averaging vs lump sum.
Either way, don't sit and wait for the perfect dip. That's market timing, and it rarely pays off.
How to invest an inheritance for the long run
Money you won't touch for years needs a simple, sturdy setup. Two decisions do most of the work.
Build a diversified core with index funds
Most long-term investors build their base with a broad index fund. One fund tracking the S&P 500 spreads your money across 500 large US companies. The cheapest ones charge 0.015% to 0.03% a year.
Individual stocks can sit on top as smaller bets. A core-satellite portfolio keeps those picks from taking over. If you do pick stocks, research them in the Stoxcraft Screener first.
Match your stock and bond mix to your time horizon
Your time horizon is how long until you need the money. The longer it is, the more volatility you can sit through.
A 25-year-old investing for retirement can hold mostly stocks. Someone who needs the money in eight years might add bonds to soften the drops. Your risk tolerance sets the final mix.
Time is the biggest edge an heir has. Even a modest sum grows fast when you leave it alone.
That's compound growth at work. It only happens if the money stays invested through the rough years.
Inheritance mistakes that drain the money fast
Many inheritances don't vanish in one crash. They leak out through a few common mistakes.
- Upgrading your lifestyle overnight. A new car and a bigger apartment eat the money that should be compounding.
- Chasing hot tips. FOMO buys in meme stocks or crypto can turn a windfall into an expensive lesson.
- Lending to family without a plan. Decide your limits before the requests start.
- Keeping everything in one inherited stock. Loyalty to a parent's pick is not a strategy.
- Selling in the first big drop. Panic selling locks in losses that patient investors ride out.
Every one of these starts with a fast decision. The fix is always the same. Slow down and follow the plan.
An inheritance lasts when the plan comes before the purchase
So how do you invest an inheritance? Slowly at first, then with conviction.
Park the cash, sort out what you inherited, and fix your foundation. Then invest the long-term money in a diversified mix you can hold through the drops. The data favors getting fully invested once the plan is set.
The heirs who keep their inheritance aren't the ones with the best picks. They're the ones who didn't rush.