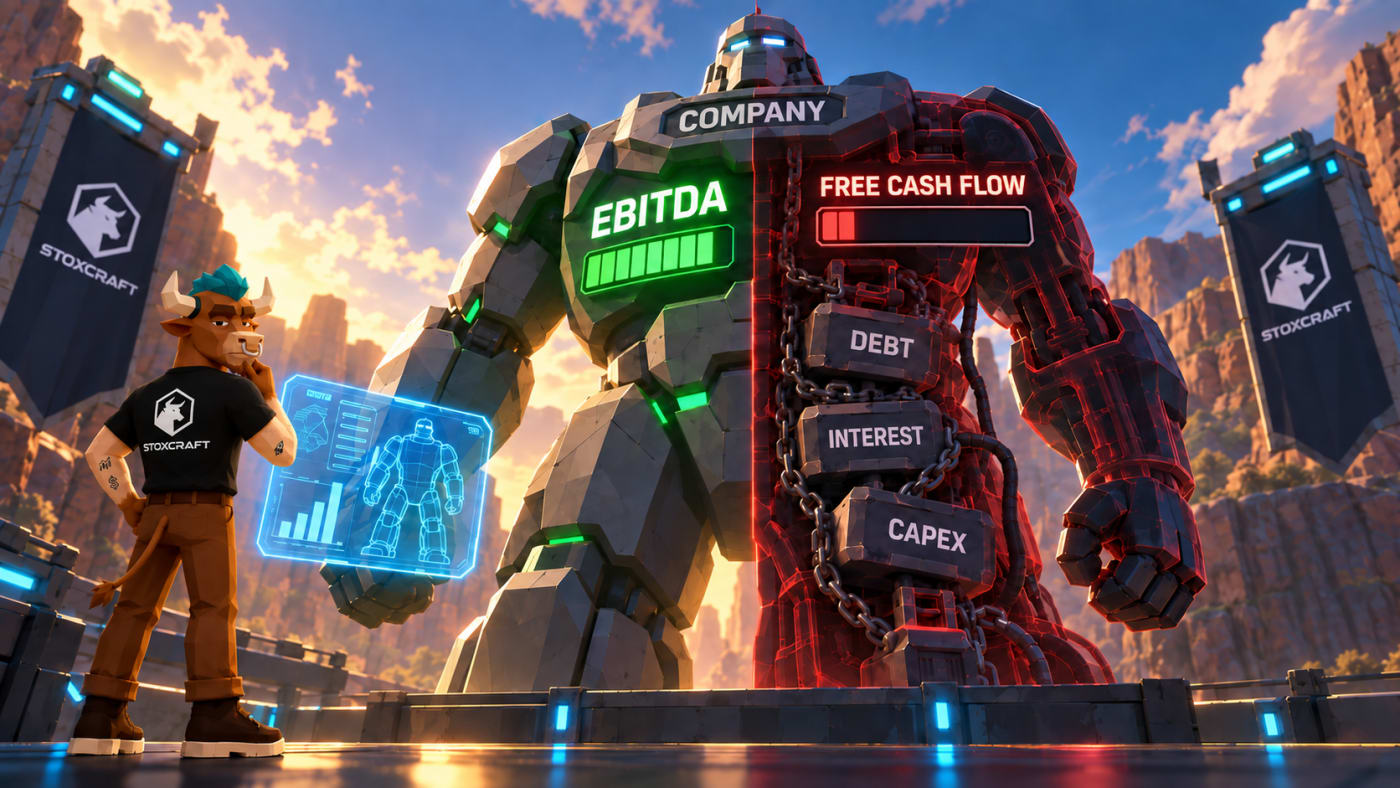
EBITDA can make a heavily indebted company look just as healthy as a debt-free one. That single number gets used to price acquisitions, compare rivals, and justify billions in borrowed money. It just does not tell you whether a company can actually service that debt.
What is EBITDA? It stands for earnings before interest, tax, depreciation, and amortization. It strips away four cost categories to show a cleaner view of operating profit.
That is useful. It is also easy to abuse. Here is what EBITDA measures, what it hides, and why smart investors never look at it alone.
What EBITDA measures
EBITDA takes net income and adds back four items: interest, tax, depreciation, and amortization. What is left is a rough measure of a company's core operating profit, before financing decisions and accounting choices get involved.
Two companies selling the exact same product can report very different net income. One carries $500 million in debt. The other has none. The debt-free company pays no interest and looks more profitable on a net income basis. Strip out interest with EBITDA, and both companies suddenly look identical.
That is the whole point of the metric. EBITDA is built to compare companies on operating performance alone, independent of how they are financed, taxed, or how old their equipment is.
Try it below. Company A carries no debt, Company B does, and both start out with the exact same EBITDA. Drag the slider up to load more debt onto Company B and watch its interest expense climb while its net income falls, even though the EBITDA line on both cards never moves.
How to calculate EBITDA
Start with net income. Then add back four things, one at a time.
You can also build it from operating income instead: take operating income and add back depreciation and amortization, since interest and tax are already excluded there. Both paths land on the same number.
Plug in a company's income statement and you will have a working EBITDA figure in under a minute. The hard part is knowing what it is not telling you.
Why analysts and companies love EBITDA
EBITDA became the standard yardstick in leveraged buyouts and private equity for one reason. It lets buyers compare companies with wildly different debt loads on a level field. A cable company loaded with debt and a debt-free software company can both get priced off the same multiple of EBITDA.
That comparability is exactly what made it easy to abuse. Think of a stock's stat sheet: EBITDA is the attack stat, and a company can juice it by editing out entire categories of damage taken. WeWork did exactly that ahead of its 2019 IPO. It did not stop at the standard four add-backs. It invented its own metric, "Community Adjusted EBITDA," and used it to also strip out marketing, design, and general administrative costs, expenses that hit every single month, not just once. That is not removing noise from the signal. That is deleting the boss's health bar and calling it a win.
Wall Street Journal reporting showed the company had lost close to $700 million in just six months, even while its adjusted metrics kept insisting the business was healthy. The gap between the two numbers was the whole story.
That is the sharp edge of the metric. Used honestly, EBITDA is a fast way to compare operating profit across companies with different debt and tax situations. Used aggressively, it turns into a marketing tool for a business that is not really making money.
EBITDA's blind spots: debt and capex
EBITDA has two structural blind spots, and both get exploited constantly. The first is debt. The second is capital spending. Here is how each one distorts the picture.
The debt blind spot
EBITDA adds back interest expense entirely. That means a company financing its growth with billions in debt reports the exact same EBITDA as a company funded entirely with equity.
Lenders use debt-to-EBITDA ratios to judge how much leverage a company is actually carrying, and that same leverage is exactly what Stoxcraft's Risk Score is built to catch. Telecom and media companies routinely take on heavy debt to fund infrastructure and content, and their EBITDA alone will not show you how much of that cash is already spoken for by interest payments. That is where the Risk Score earns its keep: a higher number there means more baked-in risk, and a heavy debt load is one of the biggest drivers of it.
Charter Communications (CHTR), T-Mobile (TMUS), and Warner Bros. Discovery (WBD) all carry the kind of debt loads that make this worth checking. Pull up their cards below and compare Health Score against Risk Score side by side. A stock can look strong on fundamentals and still carry a heavier debt burden than its peers, and that split only shows up once you stop looking at EBITDA in isolation.


The capex blind spot
Depreciation and amortization get added back too, on the logic that they are non-cash charges. But depreciation exists because equipment wears out and needs replacing. A capital-intensive business, think airlines, telecom, or manufacturing, needs to spend real cash on capex every year just to keep operating.
EBITDA ignores that spending completely. A company can report strong EBITDA while burning through cash on equipment upgrades that never show up in the number at all.
EBITDA vs free cash flow
Free cash flow fixes both blind spots at once. It starts with real operating cash flow and subtracts actual capital expenditures, the cash a company genuinely spent keeping the lights on. Debt shows up too, since interest payments hit cash flow whether or not EBITDA adds them back. Stoxcraft breaks down the full metric in its free cash flow glossary entry.
This is exactly why credit analysts got burned in the private credit boom. A 2023 Bloomberg piece described how aggressive earnings add-backs kept understating real leverage risk across debt-laden companies. The math looked fine right up until it did not.
The takeaway is not that EBITDA is useless. It is that EBITDA measures potential, and free cash flow measures reality. A company with rising EBITDA and shrinking free cash flow is telling you two different stories, and the free cash flow one usually wins.
EBITDA works, but only with cash flow standing next to it
EBITDA is a useful shortcut, not a verdict. It strips out financing and accounting noise so you can compare operating performance across very different companies. That has real value.
But EBITDA cannot tell you whether a company can pay its debt, replace its equipment, or survive a bad year. Free cash flow can. Check both, every time a stock's story leans hard on one number.