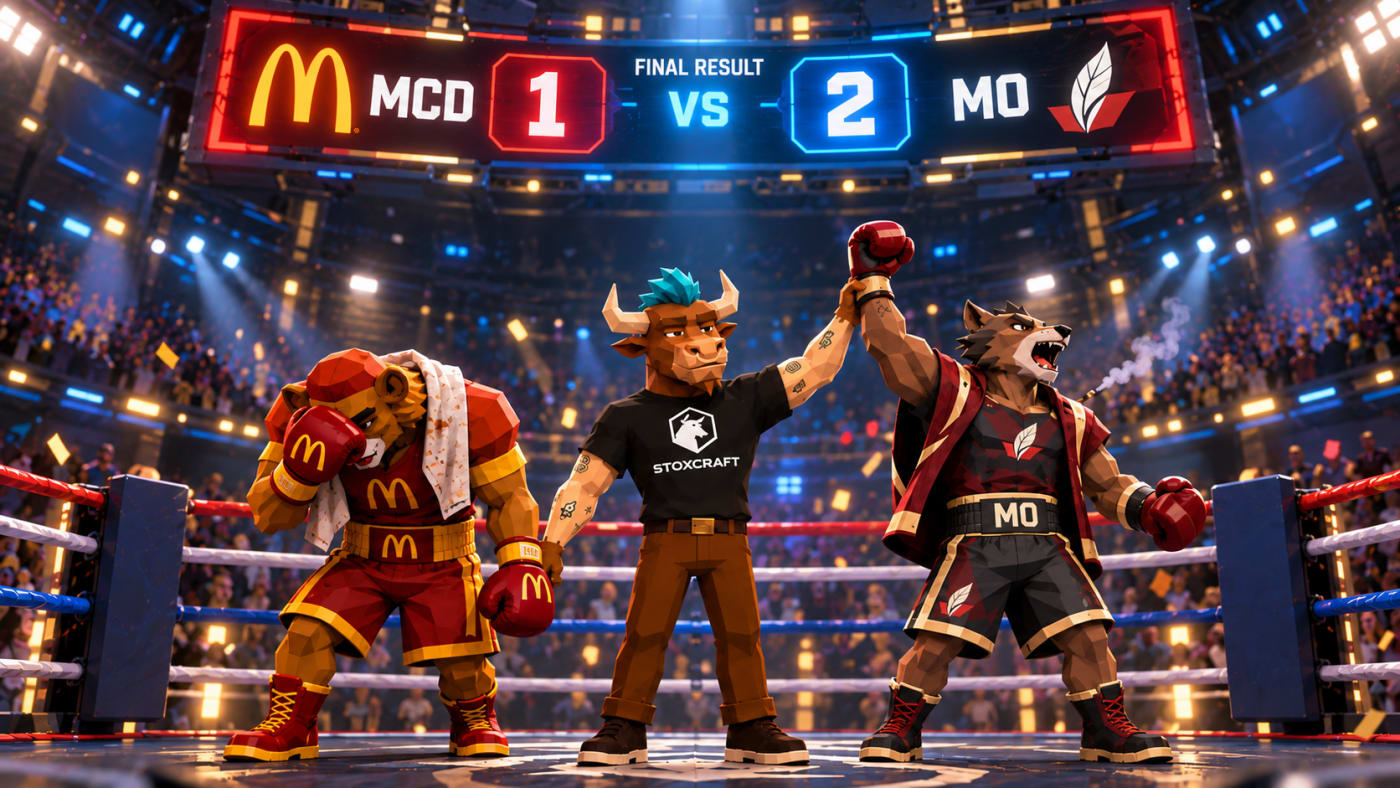
McDonald's US foot traffic fell 4.5% in the second quarter of 2026, worse than the broader quick-service industry's 3.0% drop, and the company responded by replacing the head of its US business the same day it reported earnings. That's not the profile most people have in their head when McDonald's comes up as a "safe, steady" dividend stock.
Altria sells cigarettes, a business most people assume is the riskier bet by comparison. Checked metric by metric, the reputations don't hold up, and it's the "risky" one that's actually delivering.
Here's both names side by side before the numbers start.



Three angles decide which one actually matters if you're deciding where to put money: fundamental health, the dividend behind it, and who's actually performing right now.
Round 1: Who's actually healthier?
This one is closer than either company's reputation would suggest. McDonald's (MCD) carries a 7.6 Health Score. Altria (MO) sits at 7.0. Both land well above the 5.0 average across the roughly 3,900 stocks Stoxcraft tracks, so this round comes down to six-tenths of a point, not a landslide.
Both scores are high for the same underlying reason: real, high-margin cash flow. McDonald's converts $10.55 billion a year in operating cash flow off a relatively simple licensing-and-royalty model, most of its restaurants are franchised, so it collects fees without carrying the day-to-day cost of running each location.
Altria's cash flow, $9.29 billion a year, comes from an even simpler model, a legacy product with brand loyalty strong enough to keep raising prices even as the customer base shrinks. Health Score rewards that kind of consistent, high-margin cash generation regardless of whether the underlying industry is growing or shrinking, which is exactly why a fast-food giant and a cigarette maker can both score this well while looking nothing alike on the surface.
McDonald's has spent decades building the image of the ultimate steady blue chip, and the traffic decline above doesn't actually show up here, the Health Score measures the balance sheet, not this quarter's guest counts. Altria carries the baggage of an industry in structural decline, yet its fundamentals hold up nearly as well.
Round 2: Who's paying you more to hold it?
Here's the one that should go the other way given the reputations. Altria pays a 6.15% dividend yield. McDonald's pays 3.03%, about half. Altria's yield is backed by a 36.46% net profit margin, meaning it keeps about $36 of every $100 in revenue as profit, and by a track record most dividend investors would recognize immediately: Altria is a Dividend King, on track for its 56th consecutive annual dividend increase, a streak that's outlasted decades of declining cigarette volumes. McDonald's net margin sits at 31.72%, still strong, but lower than the company paying out the bigger yield.
Both companies show negative total shareholder equity on the books, McDonald's at negative $1.79 billion, Altria's at negative $3.45 billion, the result of years of aggressive share buybacks rather than a sign either business is unprofitable. That distortion is exactly why Return on Equity isn't a useful comparison here for either name, and why margin and Altman Z-Score matter more.
Altman Z-Score is a standard bankruptcy-risk model where anything above 3.0 counts as the safe zone, and both names clear it comfortably: Altria's sits at 5.00, McDonald's at 4.68. In plain terms, neither company's dividend looks at risk of being cut for balance-sheet reasons, the real difference is simply how much of each company's profit gets paid out to shareholders versus reinvested.
Want to see what that 6.15% yield actually turns into over time? Stoxcraft's dividend calculator models the income and reinvestment growth for either stock.
Round 3: Who's actually delivering right now?
Margin and score are one thing, the stock chart is another, and it isn't close. Altria's Performance Score sits at 5.5. McDonald's sits at 0.2, near the bottom of the entire platform. Performance Score measures actual stock returns across multiple timeframes, so a low reading means the market hasn't rewarded holders lately, regardless of how healthy the underlying business looks.
McDonald's stock is down 17.37% over the past year and down 8.03% over three years, a decline that lines up with the traffic and leadership story above. Altria's stock is up 7.63% over the past year and up 62.19% over three.
Why the disconnect, if McDonald's margin and Health Score both hold up? Analyst coverage points to McDonald's roughly $40 billion debt load, where rising interest rates have pushed up borrowing costs as the company refinances, on top of comparable-sales growth that's come in weaker than investors expected. Neither issue shows up in the margin line, but both weigh directly on the stock. Altria's steady tobacco cash flow, by contrast, has kept compounding straight through the same period.
Final score: Altria 2, McDonald's 1
Altria takes the overall win because it backs up a comparable Health Score with a bigger, better-covered dividend and a stock that's actually delivered over the past three years. McDonald's isn't a weak business, its margin and Health Score both hold up, but a name with this much brand recognition still lost money for anyone holding the stock over the past year, and this quarter's traffic and leadership shakeup are exactly the kind of near-term pressure that Performance Score is picking up.
One more number worth a look before closing the tab: neither stock is priced for the story its scorecard tells. McDonald's trades at a P/E of 25.47, meaning investors are currently paying about $25.47 for every $1 of the company's annual earnings. Altria trades at a P/E of 14.03, or roughly $14.03 for every $1 of earnings, noticeably cheaper despite winning two of the three rounds above. Paying more per dollar of earnings for the name that's actually delivered less over the past three years isn't a valuation call on its own, but it's the kind of gap a value-minded investor would want to understand before assuming the higher price tag is justified.
Here's the full scorecard, both names side by side:
None of that is a buy signal. Strong fundamentals today don't guarantee strong fundamentals next quarter, and a great balance sheet has never stopped a stock from having a bad year. It's a scorecard, not a crystal ball. Curious how other dividend names stack up against each other. Stoxcraft's screener lets you filter by Health Score and Performance Score yourself.